November 2026: Washington voters rejected Initiative 645 on November 3, 2026. The measure would have repealed the 9.9% tax on income over $1 million. The tax remains on track to take effect January 1, 2028. Anyone planning a move has roughly two years to build the record that will support it. What happens next →
For decades, Washington was one of the few states without a personal income tax. That has changed. The state now has a capital gains excise tax and, from 2028, a 9.9% tax on individual income above $1 million. Both depend on who counts as a Washington resident, and for people who leave, how many days they spend in the state afterwards.
The Two Taxes
The Millionaires' Tax (RCW 82A.04)
Engrossed Substitute Senate Bill 6346 (Chapter 238, Laws of 2026), approved March 30, 2026, creates a new income tax codified at chapter 82A.04 RCW:
- Rate: 9.9% of Washington taxable income, beginning January 1, 2028 (RCW 82A.04.030).
- $1 million standard deduction, not a bare threshold: each individual deducts $1,000,000 from Washington base income, so the tax applies only to income above that amount (RCW 82A.04.360).
- Spouses share one deduction. Spouses and state-registered domestic partners get a combined $1,000,000 deduction, whether they file jointly or separately. Filing separately does not double it. For a couple who each earn just under $1 million, that difference decides whether they owe anything at all.
- Inflation indexing begins with the first adjustment in October 2029 (RCW 82A.04.367).
The Capital Gains Excise Tax (RCW 82.87)
Washington's capital gains tax applies to the sale or exchange of long-term capital assets such as stocks, bonds and business interests. It is now two-tier (RCW 82.87.040):
- 7% on Washington capital gains above the standard deduction; and
- an additional 2.9%, effective for 2025 and later, on the portion of gains above $1,000,000, for a combined 9.9% on that portion.
The standard deduction is indexed for inflation each year. It was $270,000 for 2024 and $278,000 for 2025. The Department of Revenue had not yet published the 2026 figure when this page was reviewed. See the Department of Revenue's capital gains page for the current amount.
How the Two Taxes Interact
The income tax allows a nonrefundable credit for Washington capital gains tax paid for the same tax year, starting with tax year 2028 (RCW 82A.04.130). The credit cannot exceed the income tax otherwise due. This matters for anyone timing an exit around a liquidity event. The same gain is not taxed twice at full rates, but the credit only reduces the income tax and is never refunded.
After Initiative 645: What Happens Now
Until November 3, a reader could reasonably assume the tax might not survive. Opponents first tried a referendum. The Washington Supreme Court held that the law fell within the constitutional exception for measures necessary to support state government, so it could not be referred to voters. They then qualified Initiative 645 to repeal it, and voters rejected it by a wide margin.
One avenue remains: litigation. A constitutional challenge filed in April 2026 argues that the tax is a non-uniform property tax. It relies on Culliton v. Chase (1933), in which the Washington Supreme Court treated income as property subject to the constitution's uniformity requirement and 1% limit. The state will point to Quinn v. State (2023), in which the same court upheld the capital gains tax as an excise rather than a property tax. The income tax is drafted as a tax on the "receipt" of income, so it is built to fit within Quinn, although it is a broader tax than the one Quinn considered.
The practical conclusion: a case that begins in a trial court and ends in the Washington Supreme Court is unlikely to be finally resolved before January 1, 2028. A taxpayer who waits for the courts and loses has also lost the planning window. Plan as though the tax applies, and treat a successful challenge as a bonus.
Who Is a Washington Resident?
The income tax has its own residency definition at RCW 82A.04.010(8). It closely tracks the capital gains definition. You are a resident if you meet either test below.
1. The Domicile Test
If you are domiciled in Washington, you are a resident unless all three of the following are true for the taxable year:
- You maintained no permanent place of abode in Washington during the entire taxable year;
- You maintained a permanent place of abode outside Washington during the entire taxable year; and
- You spent in the aggregate not more than 30 days of the taxable year in Washington.
2. The Statutory Residency Test (183 Days)
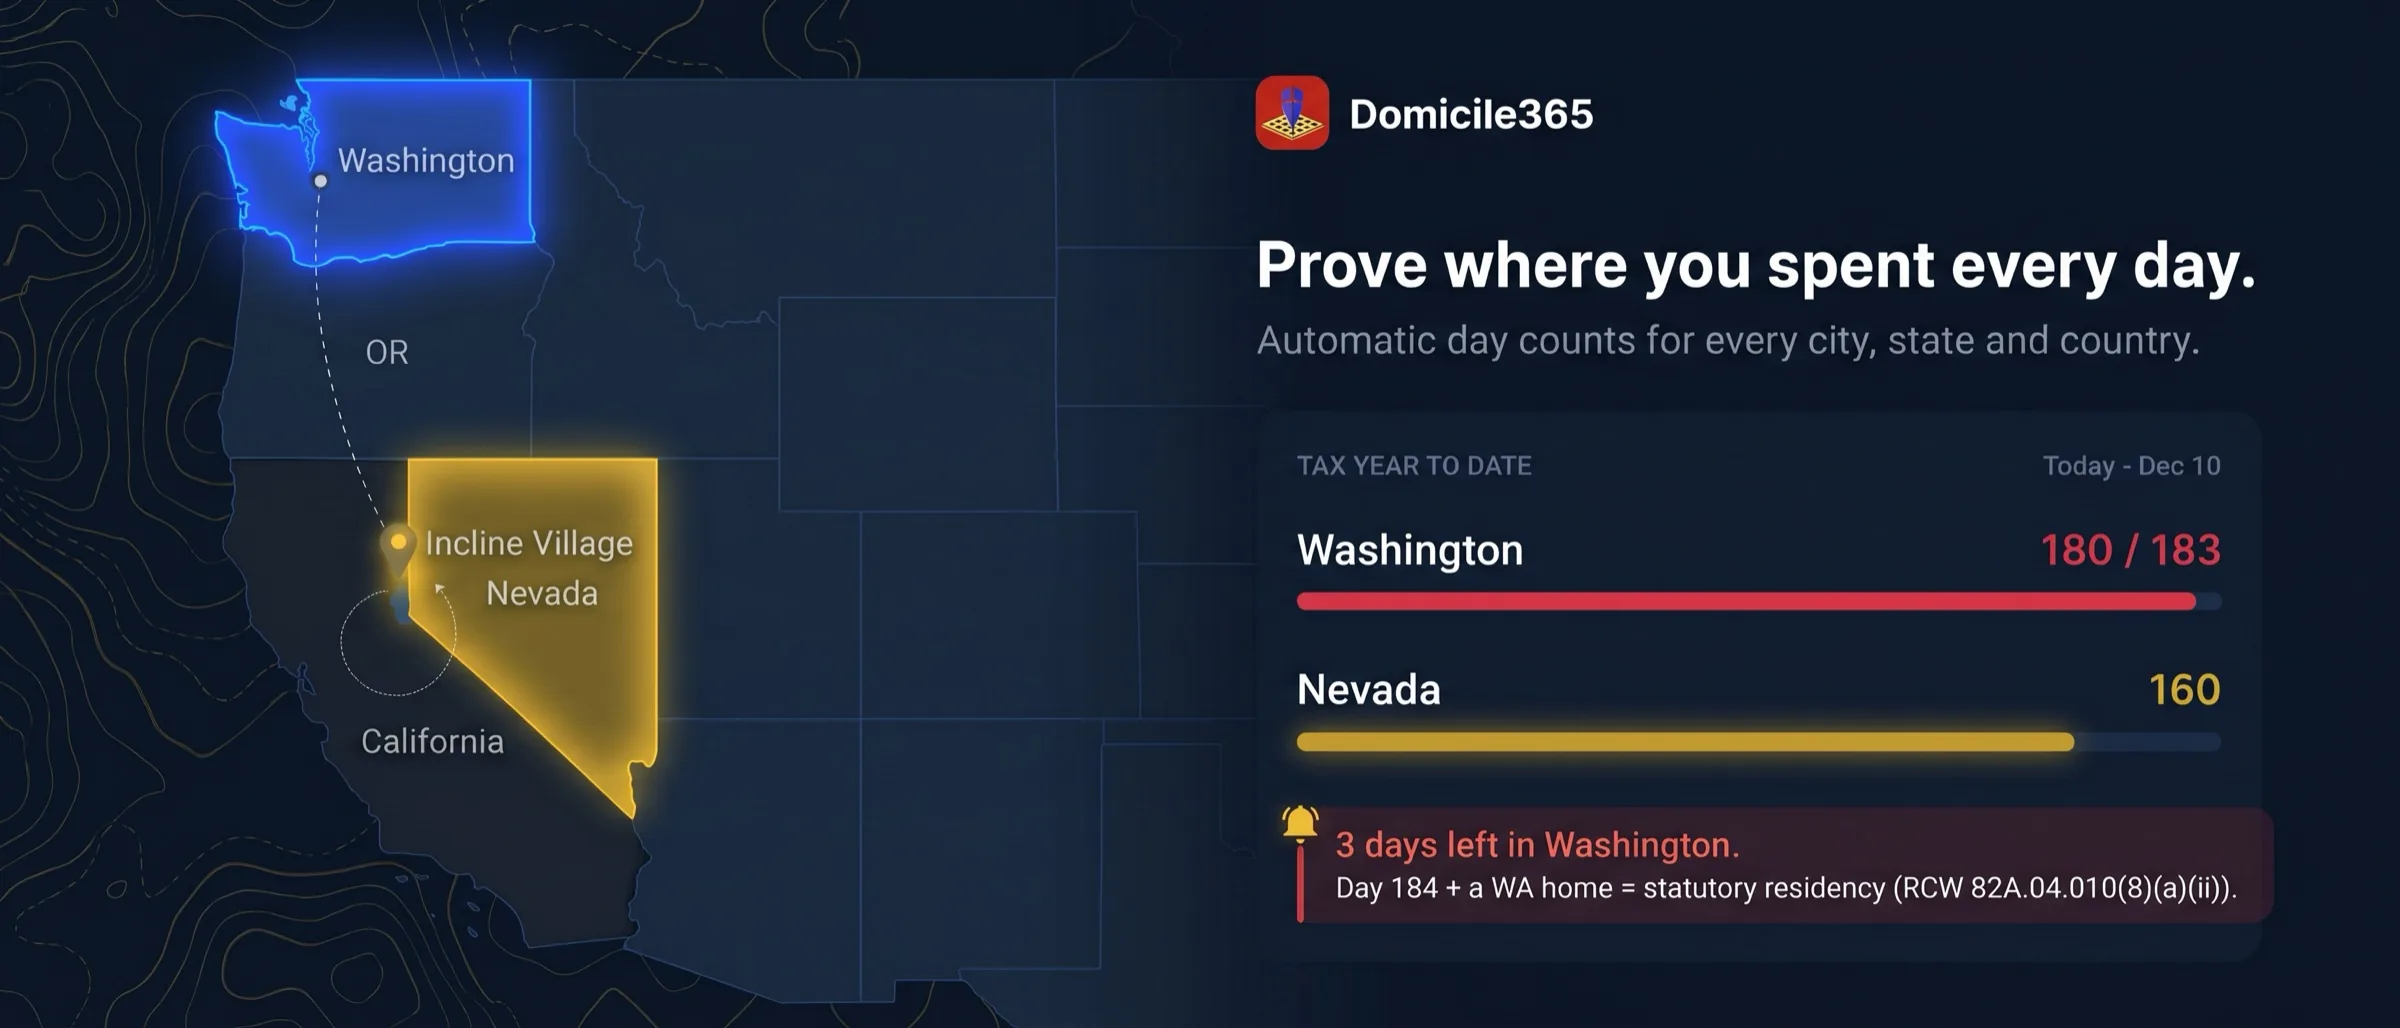
Even if you are not domiciled in Washington, you are a resident if you maintained a place of abode in Washington and were physically present in the state for more than 183 days during the taxable year.
What Counts as a Day
For residency purposes, a "day" is a calendar day or any portion of a calendar day. A morning meeting in Bellevue counts the same as a full day at home. So does a connecting flight through Sea-Tac, at least on the statute's plain words. How Washington will treat pure transit has not been settled. We cover the general issue in Transit Days and Tax Residency.
Leaving Washington Does Not End Your Exposure
Many people assume that once they move, Washington can no longer tax them. Under the new law, nonresidents are still taxed on Washington-source income (RCW 82A.04.410(2)), which includes:
- Wages and other compensation for work performed in Washington;
- Income from a business, trade or profession carried on in Washington, including your share of income from a pass-through entity operating in the state;
- Rents and gains from real or tangible personal property located in Washington;
- Income from intangible property, such as dividends, interest and gains, to the extent the property is employed in a business carried on in Washington;
- Compensation of professional athletes and name, image and likeness income of student athletes, sourced under their own rules; and
- Wagering income.
Someone who moves to Nevada but keeps flying back to work in a Seattle office, keeps a share of a Washington operating business, or holds Washington rental property is still within the tax for that income.
The Five-Day Rule
There is one important exception. Under RCW 82A.04.410(3), if a nonresident performs services in Washington five or fewer days cumulatively in a calendar year, no income is allocated to Washington under the sourcing section. The exception does not apply to nonresident professional athletes, student athletes or entertainers.
This is the tightest day count in the statute. Take a former Washington resident who now consults for a Seattle company from out of state. They have five days of headroom a year. A sixth day spent working in the state, even part of a day, ends the exception for that year. If the Department of Revenue asks, they will need to show which days they were in Washington and which they were not. The statute is new and the Department has not yet issued rules on how far the exception reaches, so confirm its application to your income with your advisor.
Part-Year Residents
In the year you arrive or leave, you are a resident only for the portion of the year in which you were domiciled in Washington or maintained a place of abode there (RCW 82A.04.010(8)(c)). Under RCW 82A.04.450:
- For the resident portion, all of your adjusted gross income is taxed;
- For the nonresident portion, only Washington-source income is taxed; and
- Items from a pass-through entity are prorated by the ratio of the days you were a resident (and a nonresident) to the days in the entity's tax year.
That proration is a day-count calculation written into the statute. The date your Washington residency ended affects how much tax is due, so you need to be able to prove it.
The Day Counts That Matter
| Threshold | Who it affects | Source |
|---|---|---|
| 5 days of work in Washington | Nonresidents earning compensation for services, apart from athletes and entertainers | RCW 82A.04.410(3) |
| 30 days in Washington | Washington domiciliaries claiming the non-resident exception | RCW 82A.04.010(8)(a)(i) |
| More than 183 days in Washington | Non-domiciliaries who keep a place of abode in the state | RCW 82A.04.010(8)(a)(ii) |
| Residency days in a move year | Part-year residents with pass-through income | RCW 82A.04.450 |
Establishing non-residency takes more than intent or an after-the-fact estimate. It takes contemporaneous evidence of where you were each day. Audits of 2028 and later years will look at the years before them for patterns of domicile and presence, so the record for 2026 and 2027 matters too.
Moving to Nevada solves only part of the problem if you then spend significant time in California. California applies its own residency tests, and a move away from Washington can create a new exposure there. See California Residency Rules.
Compliance Dates
- January 1, 2028: the tax applies to income received from this date.
- April 2029: first returns and payments are due, on the federal return due date (RCW 82A.04.550). A federal extension extends the time to file but not the time to pay.
- Estimated payments are required when estimated tax exceeds $5,000, but none are required before July 1, 2029 (RCW 82A.04.510).
Official Sources
- ESSB 6346, Chapter 238, Laws of 2026: the enacted law, approved March 30, 2026. (PDF copy)
- RCW 82A.04.010(8): resident definition, 30-day exception, "day", and part-year residency.
- RCW 82A.04.410(2) and (3): nonresident source income and the five-day rule.
- RCW 82A.04.450: part-year allocation.
- Chapter 82A.04 RCW: rate, standard deduction, capital gains credit, returns and estimated payments. (PDF copy of full chapter)
- Chapter 82.87 RCW: capital gains excise tax. (PDF copy of full chapter)
PDF copies were saved from the Washington State Legislature on November 11, 2026. The legislature's site is the current authoritative text.
This article is general information, not legal or tax advice. The income tax is new, the Department of Revenue has not yet issued implementing rules, and litigation is pending. Confirm how the law applies to you with a qualified advisor.
Defend Your Residency Status
Don't rely on inadequate records. Use the Domicile365 App to create a defensible, GPS-based log of your location.
Sign up for a free 60-day trial and start tracking today.
Advising clients on a Washington exit? See Domicile365 for Advisors & CPAs.